
Have You Reviewed Your Tennessee ORP Recently?
Your retirement account has worked hard for years.
But have you reviewed what it may actually provide in retirement?
If you participate in Tennessee's Optional Retirement Program (ORP), you've likely spent years contributing to retirement accounts with providers such as TIAA, Corebridge, or Voya.
Your account statement tells you how much you've accumulated.
But it doesn't necessarily answer the questions that become most important as retirement gets closer.
How much retirement income could these accounts actually provide?
When is the best time to begin taking income?
Should you leave everything where it is?
Are there other retirement income strategies worth comparing?
How does your ORP fit together with Social Security and other retirement accounts?
Those are the questions an independent retirement review is designed to answer.

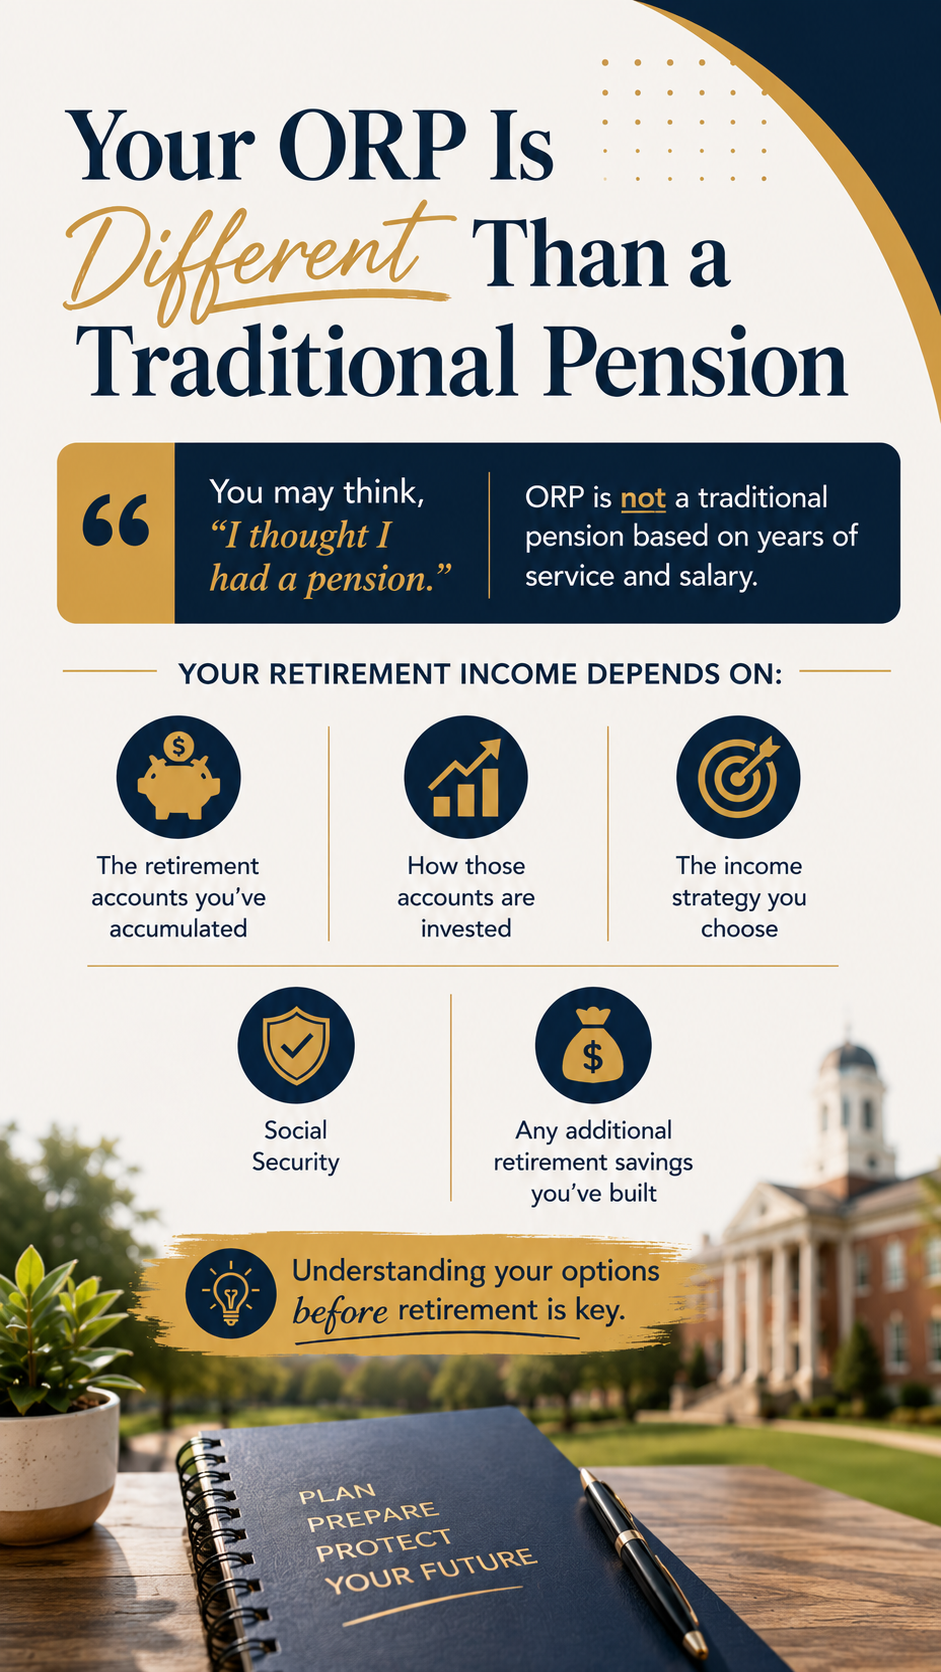
Your ORP Is Different Than a Traditional Pension
One of the biggest misconceptions I hear from higher education employees is:
"I thought I had a pension."
Many employees are familiar with pension formulas based on years of service and salary.
However, participants in Tennessee's Optional Retirement Program (ORP) generally do not receive a traditional pension calculated using that formula.
Instead, your retirement income depends largely on:
-The retirement accounts you've accumulated
-How those accounts are invested
-The income strategy you choose when you retire
-Social Security
-Any additional retirement savings you've built
That's why understanding your options before retirement is so important.
Your Retirement May Include More Than One Account
Many higher education employees have retirement savings spread across several places.
Your retirement picture may include:
✔ Tennessee ORP
✔ 401(k)
✔ 403(b)
✔ 457 Plan
✔ Retirement accounts from previous employers
✔ Roth IRA or Traditional IRA
✔ Social Security
Sometimes people are surprised to discover retirement accounts they had forgotten about or simply hadn't included in their retirement planning.
Looking at everything together often provides a much clearer picture.
Have You Ever Compared Your Current Provider With Other Options?
If your retirement savings are currently invested with one provider, such as TIAA, Corebridge, or Voya, it's natural that most of the retirement options you see come from that provider.
That doesn't necessarily mean those options aren't appropriate.
It simply means you may not have seen what else is available.
An independent retirement income review allows you to compare retirement income strategies from more than 15 highly rated insurance companies so you can better understand how different approaches work.
Sometimes your current plan remains the best choice.
Sometimes another strategy may better align with your retirement goals.
The objective isn't to replace what you have it's to help you make informed decisions based on a broader understanding of your options.
During your ORP review, we can discuss questions like: * What could my ORP realistically provide as retirement income?
* How do guaranteed lifetime income strategies compare with systematic withdrawals?
* What happens if the market declines after I retire?
* Should I begin taking income immediately or wait?
* How does Social Security fit into my overall retirement plan?
* Are there retirement accounts from previous employers that should be included?